Listen to this article:
It is difficult to find a market conversation today that does not eventually lead back to interest rates.
For Canadian advisors, there are particularly good reasons to be paying attention. U.S. Treasury yields have moved materially higher from late-2025 levels, creating renewed questions around valuations and the outlook for rate-sensitive assets. This is not only a U.S. story. The Bank of Canada has now held its policy rate through seven consecutive decisions1, while the U.S. Federal Reserve resumed raising rates in September, marking its first hike since 20232. A Canadian advisor evaluating a USD-denominated U.S. multifamily allocation today is therefore weighing a currency and cross-border question that a U.S. advisor considering the same asset is not. At the same time, recent experiences across private real estate and private credit, in both Canadian and U.S. markets, have brought renewed attention to how less-liquid investments fit within client portfolios.
Against that backdrop, it is reasonable for advisors to be asking harder questions about any new private-market allocation.
From our perspective as investors in U.S. multifamily, that raises an important question: what does today’s environment mean for U.S. multifamily assets—and where does the asset class fit when downside protection matters more than maximizing upside?
For Canadian advisors, the starting point is not simply whether U.S. multifamily is attractive as an asset class. It is what role an allocation is intended to play within a client’s portfolio.
For investors considering income-oriented alternatives, U.S. multifamily can sit alongside allocations such as private credit and other private investments within the less-liquid portion of a portfolio. But investments that occupy the same portfolio allocation do not necessarily carry the same underlying risks.
There is a meaningful difference between lending to an operating company through private credit, investing in real estate development or value-add strategies, and owning a diversified portfolio of stabilized, income-producing U.S. multifamily assets.
Class B U.S. multifamily is particularly interesting in this context. Housing is a fundamental need. Properties generate recurring rental income from a broad tenant base, and relatively short lease terms allow rents to reset as market conditions evolve. In markets supported by employment, population and household demand, these characteristics can provide durability through different economic environments.
For an advisor considering the income-oriented, less-liquid portion of a portfolio, the relevant question is therefore not simply how much liquidity an investment provides. It is what underlying risks an investor is assuming in exchange for the income and return potential the investment is expected to provide.
That does not eliminate risk. It provides a more useful framework for understanding where the risk resides.
The significant move higher in U.S. Treasury yields since late 2025 has understandably raised questions about real estate valuations.
Higher long-term U.S. bond yields increase required returns, affect financing costs and can place downward pressure on real estate values. But the relationship between U.S. Treasury yields and U.S. multifamily cap rates is not mechanical.
CBRE’s H1 2026 Cap Rate Survey illustrates the point. The U.S. 10-year Treasury yield rose substantially during the first half of 2026, peaking near 4.67% in May, while the average cap rate across commercial property types remained essentially flat over the same period. A change in the cost of government borrowing does not translate automatically into an equivalent change in what investors are willing to pay for real assets. The degree of movement varies by property type and by market, which is exactly why today’s entry price matters more than any single benchmark.3
For investors, that creates an important distinction between interest-rate risk and valuation risk
Higher U.S. bond yields can create pressure on asset values. But for a new investor, the relevant question is not what an asset was worth when rates were lower. It is what price is being paid today for the income and long-term value of the asset being acquired.
Periods of uncertainty can create opportunities to acquire fundamentally strong U.S. multifamily assets at valuations that better reflect today’s cost of capital, rather than the exceptionally low cap rates and financing costs that characterized the previous cycle.
That does not make an investment immune from further valuation pressure. Entry price matters precisely because the future path of U.S. Treasury yields is uncertain. Buying well can create an additional layer of downside protection alongside durable property-level income, appropriate leverage and a long-term investment horizon.
There is also a structural offset worth naming. Unlike a fixed-coupon Treasury bond, multifamily income is not fixed: leases reset on a regular cycle, allowing rents, and the income the asset produces, to adjust with inflation over time. That does not eliminate rate risk, but it means that to the extent a given move in Treasury yields reflects near-term inflation concern rather than a durable rise in real rates, the pressure on long-term asset value may prove more temporary than the headline yield move suggests. Investors cannot resolve in advance whether a given move is inflation-driven or structural. But it is worth asking, of any rate move, which one is actually being priced.
The same discipline is required when considering supply.
Certain U.S. markets are still absorbing a significant wave of new multifamily construction, creating near-term pressure on rents and occupancy. That should not be dismissed.
But supply is highly market-specific, and the picture is changing. New construction is slowing, while recently delivered units continue to be absorbed. CBRE reported that net absorption exceeded new completions in both the first and second quarters of 2026, while Q2 completions declined 14% year over year.4
For investors, the question is therefore not simply whether U.S. multifamily is experiencing supply pressure. It is which markets are oversupplied, whether that imbalance is temporary or structural, what is driving long-term demand, and whether today’s valuation appropriately compensates an investor for the period required for that supply to be absorbed.
For Class B U.S. multifamily assets in fundamentally strong markets, temporary supply pressure can create near-term operating challenges without necessarily impairing the long-term investment thesis. For a long-term investor with the ability to be selective, those periods can also create opportunities to acquire quality assets at more attractive valuations.
A market is not oversupplied in isolation; it is oversupplied relative to demand, and the two move together more than headline construction figures suggest. In a higher-rate environment, homeownership becomes less affordable for a wider range of households, which can keep renters in the rental pool longer and draw in households who might otherwise have bought. That dynamic will not fully offset every market’s supply wave, but it is part of the equation, not a footnote to it.
Targeting a largely finite pool of existing, well-located assets, rather than new construction, can provide a related form of protection. Assets acquired and operated below today’s replacement cost carry more latitude to compete on rent against newly delivered supply, because the owner is not required to achieve rents sized to justify ground-up construction costs in order to generate an attractive return.
The distinction is important: a good asset is not necessarily a good investment at any price, and a temporarily challenged market is not necessarily a poor investment at the right price.
The investment question today is not simply whether U.S. Treasury yields go higher or lower from here. For advisors considering the income-oriented, less-liquid portion of a client’s portfolio, the more useful question is whether an investment has been constructed to protect against the things investors cannot reliably predict.
That starts with what an investor owns and what they pay for it. How the investment is structured, financed and diversified matters just as much. It is reasonable for advisors to ask of any manager, including us, how much leverage is used, how the debt is structured and when it comes due, and how concentrated the portfolio is by market and asset.
Uncertainty does not eliminate risk.
It makes what you own, what you pay for it, and how you own it matter that much more.
(1) Bank of Canada, press conference following the policy rate announcement, September 2, 2026.
(2) Board of Governors of the Federal Reserve System, “Federal Reserve issues FOMC statement,” press release, September 16, 2026.
(3) CBRE, U.S. Cap Rate Survey H1 2026, August 2026.
(4) CBRE, “U.S. Multifamily Fundamentals Improve in Q2 2026 as Demand Outpaces New Supply,” press release, August 12, 2026.
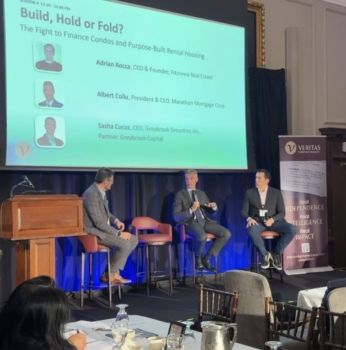
Greybrook Securities CEO Sasha Cucuz recently joined fellow industry leaders to tackle the economic pressures shaping the future of Canadian housing. Speaking at the Veritas 14th Annual Great Canadian Real Estate Conference, Cucuz participated in a highly anticipated panel discussion…
Listen to this article: It is difficult to find a market conversation today that does not eventually lead back to interest rates. For Canadian advisors, there are particularly good reasons to be paying attention. U.S. Treasury yields have moved materially…
Last season, Greybrook became the first-ever lead sponsor of York Lions Men’s Hockey. This year, extending that support to the women’s program was a natural next step and reflects something we believe deeply: sport shapes future leaders. It is an…
Greybrook team members rode in support of the 7th Annual Velo Blu Charity Bike Ride in Niagara-on-the-Lake, helping raise $270,000 to advance research into rare childhood diseases and gene therapy through the Blu Genes Foundation. Held at the scenic Peller…
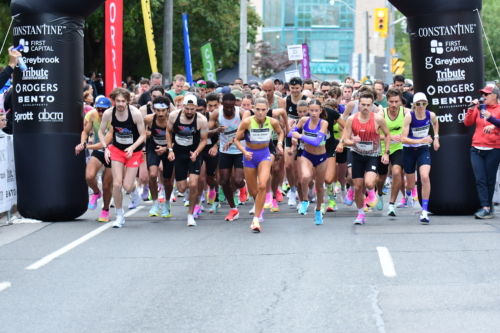
On Sunday, September 20, Greybrook joined runners, walkers, volunteers and community supporters at the 17th Annual Constantine Yorkville Run, coming together to raise funds for charities making a difference across Toronto. As a Presenting Partner, Greybrook was proud to once…
Members of Greybrook’s Institutional Capital Markets team recently attended and sponsored Future Proof Festival, the world’s largest four-day wealth management festival, held in Huntington Beach, California. As part of its sponsorship, Greybrook supported the QWealth Canadian Lounge, a dedicated gathering…
Lindsay Heights, our low-rise, master-planned community in the City of Kawartha Lakes, is set to welcome one of its most anticipated neighbourhood retail additions with the opening of a Walmart Supercentre. Located at the northwest corner of Lindsay, at Highway…

This advancement marks a significant milestone for Florida’s first supertall Downtown Miami residence, a signature hallmark of the renowned Waldorf Astoria brand, offering a collection of 205 luxury hotel guestrooms, dedicated five-star service and once-in-a-lifetime experiences. Construction of the staggered…
Listen to this article: The best time to buy durable assets is rarely the moment they feel comfortable to buy. In multifamily, rent growth tells you where a market is today, but the conditions that signal where it is heading…
Dallas-Fort Worth has been one of the most closely watched multifamily markets in the United States over the past several years. Long-term population and employment growth, rapid corporate relocations, relative affordability and a deep, diversified economy have helped draw a…